Question #171627

A trust fund is planning to invest up to $6000 in two types of bonds.: A and B. Bond A is safer than bond B and carries a dividend of 8% while bond B carries a dividend of 10%. Suppose that the bond’s rule state that no more than $4000 may be invested in bond B, while at least $1500 must be invested in bond A. The amount invested in bond B cannot exceed one half the amount invested in bond A. How much should be invested in each type of bond to maximize the fund’s return?


Expert's answer

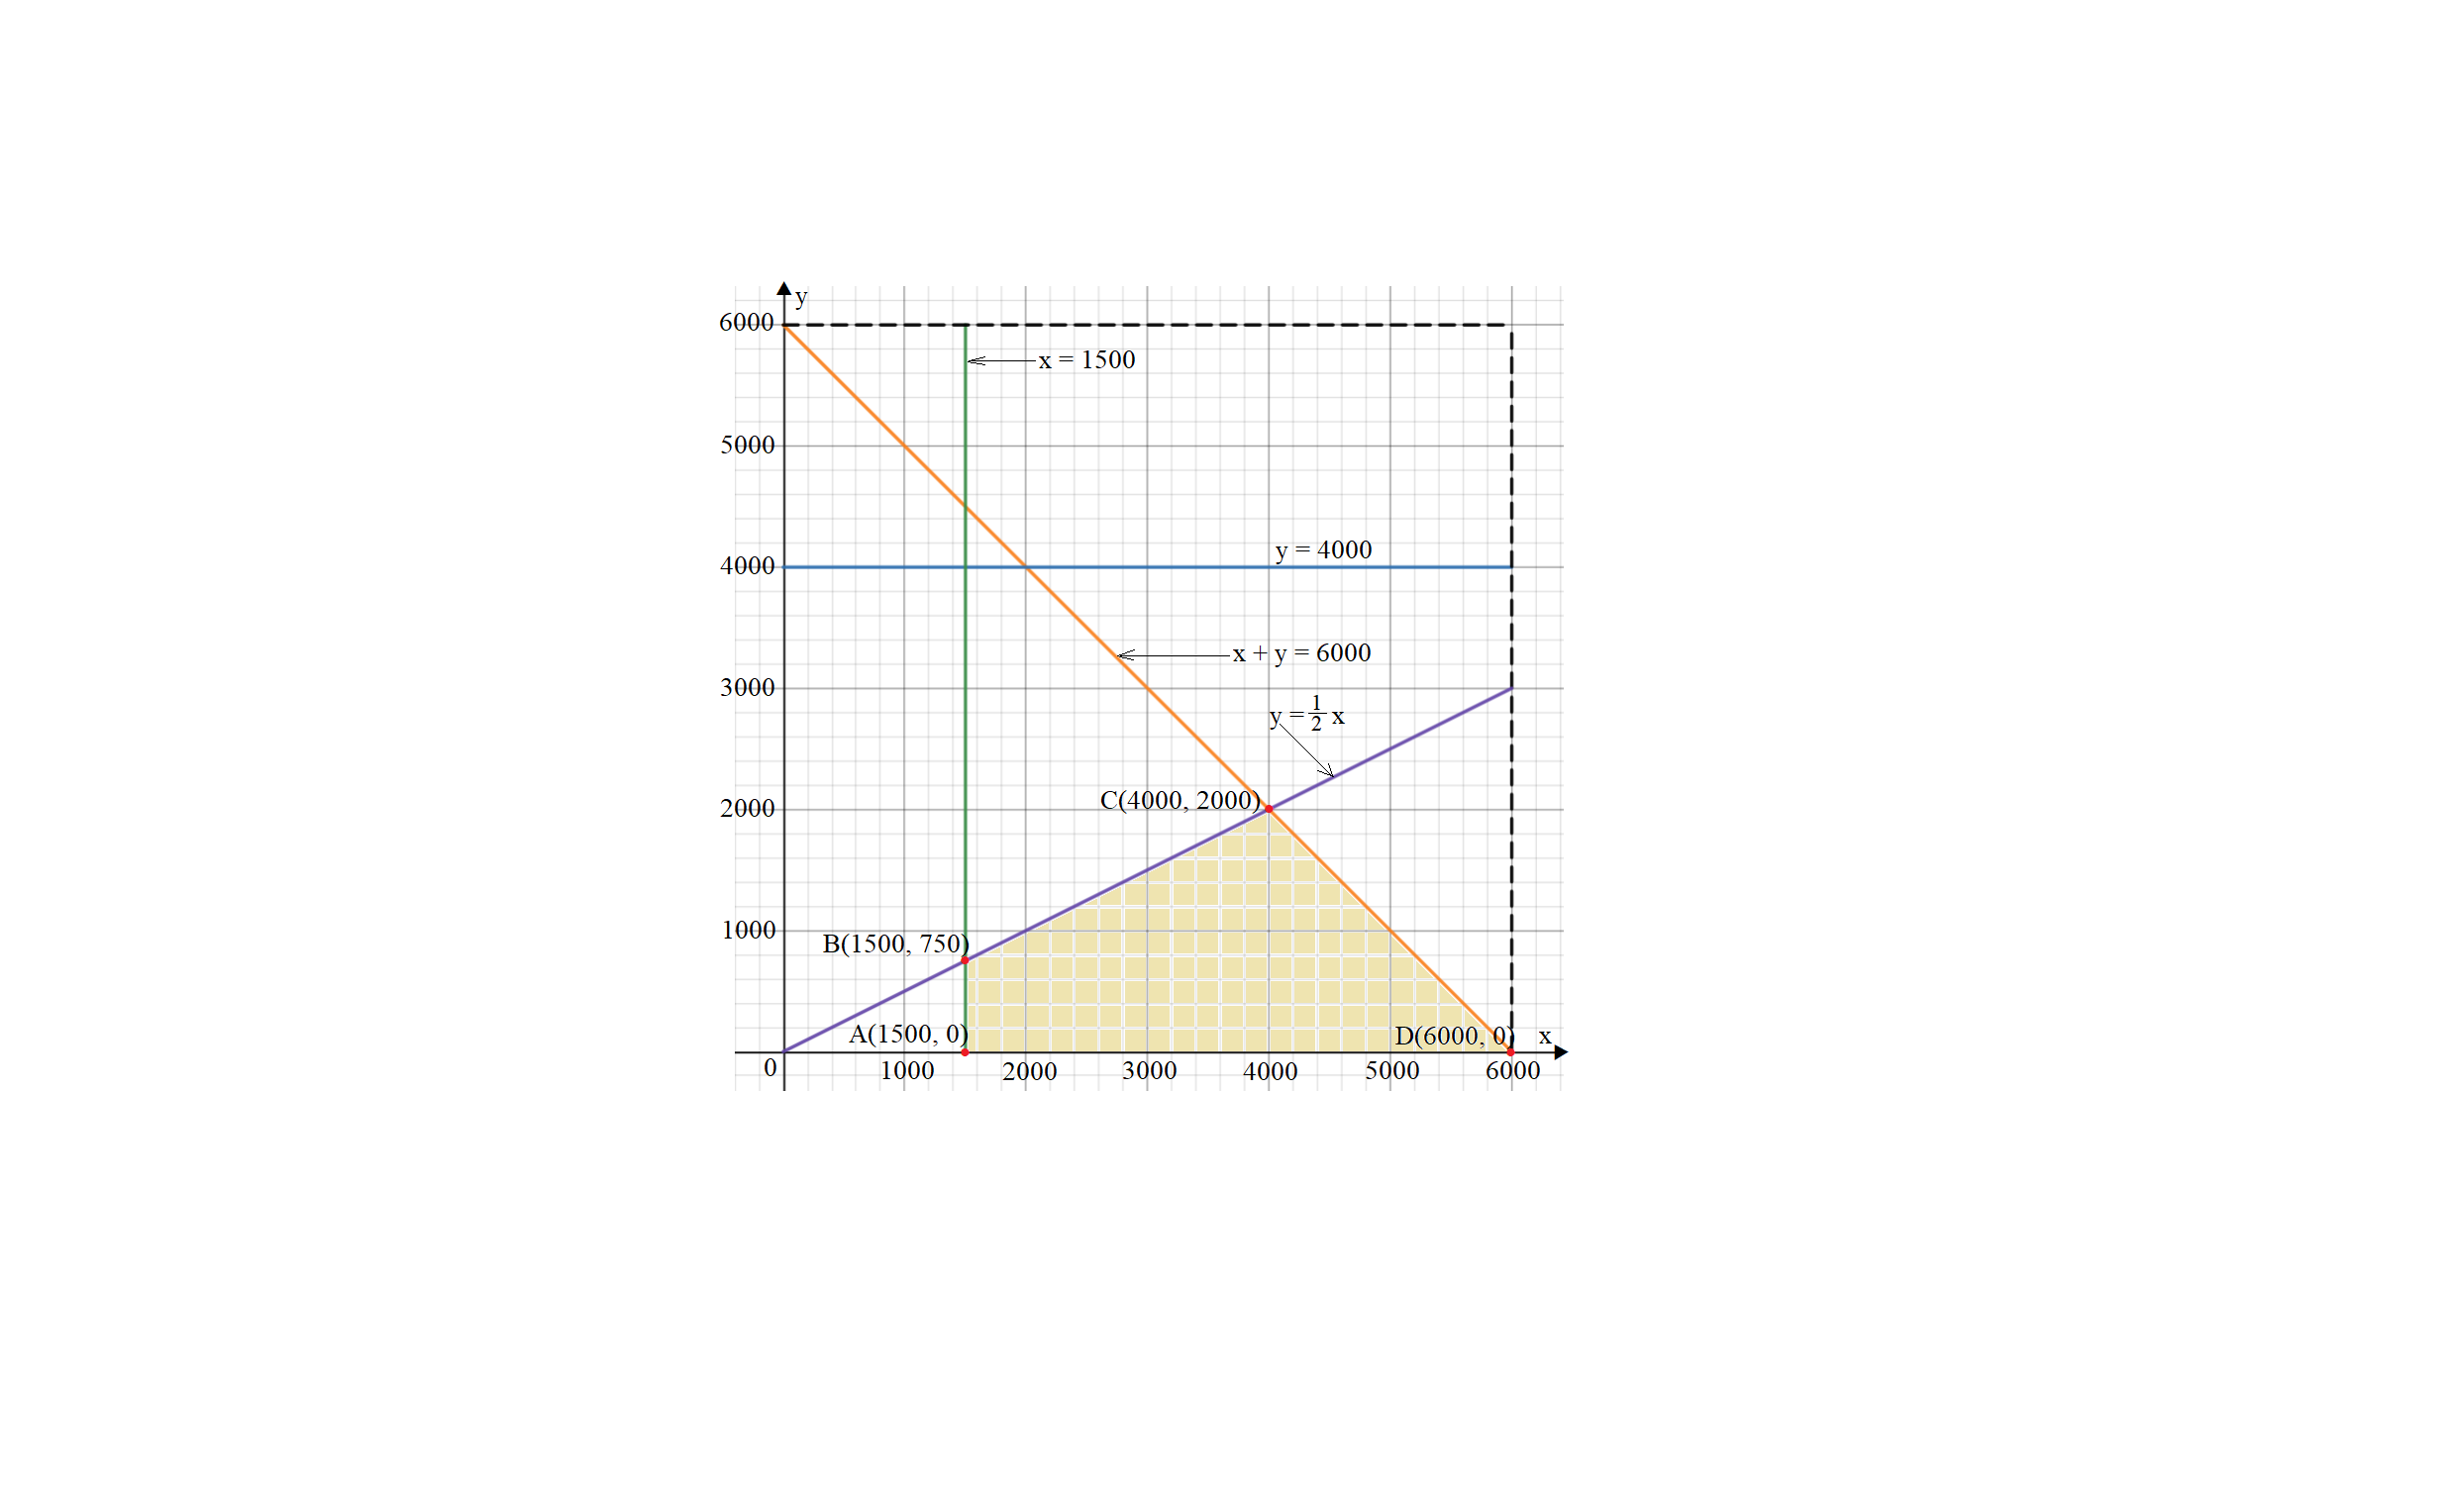
x=x= amount invested in A bonds

y=y= amount invested in B bonds


x+y≤6000x+y\leq6000

0≤y≤40000\leq y\leq4000

x≥1500x\geq1500

y≤12xy\leq\dfrac{1}{2}x

Our linear optimization problem is:

Maximize z=0.08x+0.1yz=0.08x+0.1y subject to


x+y≤6000x+y\leq6000

0≤y≤40000\leq y\leq4000

x≥1500x\geq1500

y≤12xy\leq\dfrac{1}{2}x


SegmentEquationz=0.08x+0.1yABx=1500,z=120+0.1y0≤y≤750BCy=12x,z=0.13x1500≤x≤4000CDy=6000−x,z=600−0.02x4000≤x≤6000DAy=0,z=0.08x1500≤x≤6000\def\arraystretch{1.5} \begin{array}{c:c:c} Segment & Equation & z=0.08x+0.1y \\ \hline AB & x=1500, & z=120+0.1y\\ & 0\leq y\leq 750 & \\ \hdashline BC & y=\dfrac{1}{2}x, & z=0.13x \\ & 1500\leq x\leq 4000 & \\ \hdashline CD & y=6000-x, & z=600-0.02x \\ & 4000\leq x\leq 6000 & \\ \hdashline DA & y=0, & z=0.08x \\ & 1500\leq x\leq 6000 & \\ \hdashline \end{array}


Pointz=0.08x+0.1yA(1500,0)z=120B(1500,750)z=195C(4000,2000)z=520D(6000,0)z=480\def\arraystretch{1.5} \begin{array}{c:c} Point & z=0.08x+0.1y \\ \hline A(1500, 0) & z=120\\ \hdashline B(1500, 750) & z=195 \\ \hdashline C(4000, 2000) & z=520 \\ \hdashline D(6000, 0)& z=480 \\ \hdashline \end{array}


Because the point (4000,2000)(4000, 2000) produces the highest fund’s return we conclude that $4000 should be invested in


How much should be invested in bond A and $2000 should be invested in bond B.


LATEST TUTORIALS
APPROVED BY CLIENTS